
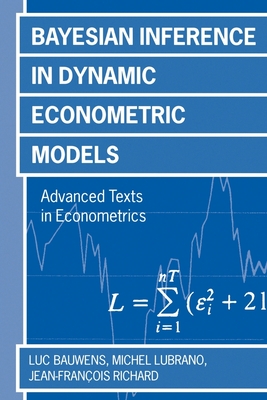
Bayesian Inference in Dynamic Econometric Models
Book Details
Format
Paperback / softback
Book Series
Advanced Texts in Econometrics
ISBN-10
0198773137
ISBN-13
9780198773139
Publisher
Oxford University Press
Imprint
Oxford University Press
Country of Manufacture
GB
Country of Publication
GB
Publication Date
Jan 6th, 2000
Print length
366 Pages
Weight
514 grams
Dimensions
23.40 x 15.70 x 2.10 cms
Product Classification:
EconometricsProbability & statisticsMathematical modelling3D graphics & modelling
KSh 14,400.00
Temporarily out of stock, due soon
0 in stock
Delivery Location
Delivery fee: Select location
Secure
Quality
Fast
This work contains an up-to-date coverage of the last 20 years' advances in Bayesian inference in econometrics, with an emphasis on dynamic models. Several examples illustrate the methods.
This book contains an up-to-date coverage of the last twenty years advances in Bayesian inference in econometrics, with an emphasis on dynamic models. It shows how to treat Bayesian inference in non linear models, by integrating the useful developments of numerical integration techniques based on simulations (such as Markov Chain Monte Carlo methods), and the long available analytical results of Bayesian inference for linear regression models. It thus covers a broad range of rather recent models for economic time series, such as non linear models, autoregressive conditional heteroskedastic regressions, and cointegrated vector autoregressive models. It contains also an extensive chapter on unit root inference from the Bayesian viewpoint. Several examples illustrate the methods.
Get Bayesian Inference in Dynamic Econometric Models by Jean-Francois Richard, Luc Bauwens at the best price and quality guaranteed only at Werezi Africa's largest book ecommerce store. The book was published by Oxford University Press and it has 366 pages.
Customers Who Bought This Also Bought
Lean Analytics – Use Data to Build a Better Startup Faster
KSh 5,750.00
Fooled by Randomness
KSh 3,400.00
Capital and Ideology
KSh 7,450.00
Microeconomics, Global Edition
KSh 15,500.00

The Power of Darkness
KSh 2,000.00

National Accounts Statistics
KSh 16,050.00

Microstructure, Statistical Fluctuations, and Technical Signals in Rational Asset Pricing
KSh 24,650.00
Progress Towards the Sustainable Development Goals in the Arab Region in 2026
KSh 3,700.00
Game Theory
KSh 45,000.00
Essays in Nonlinear Time Series Econometrics
KSh 22,950.00
A Concise Introduction to Econometrics
KSh 18,900.00
A Dynamic Approach to Economic Theory
KSh 33,850.00

