
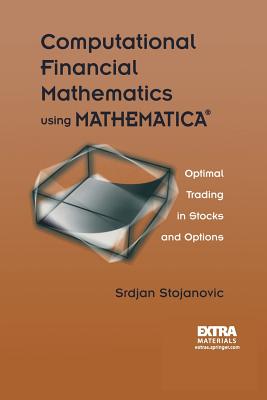
Computational Financial Mathematics using MATHEMATICA® : Optimal Trading in Stocks and Options
Softcover reprint of the original 1st ed. 2003
Book Details
Delivery Location
Delivery fee: Select location
Given the explosion of interest in mathematical methods for solving problems in finance and trading, a great deal of research and development is taking place in universities, large brokerage firms, and in the supporting trading software industry. Mathematical advances have been made both analytically and numerically in finding practical solutions.
This book provides a comprehensive overview of existing and original material, about what mathematics when allied with Mathematica can do for finance. Sophisticated theories are presented systematically in a user-friendly style, and a powerful combination of mathematical rigor and Mathematica programming. Three kinds of solution methods are emphasized: symbolic, numerical, and Monte-- Carlo. Nowadays, only good personal computers are required to handle the symbolic and numerical methods that are developed in this book.
Key features: * No previous knowledge of Mathematica programming is required * The symbolic, numeric, data management and graphic capabilities of Mathematica are fully utilized * Monte--Carlo solutions of scalar and multivariable SDEs are developed and utilized heavily in discussing trading issues such as Black--Scholes hedging * Black--Scholes and Dupire PDEs are solved symbolically and numerically * Fast numerical solutions to free boundary problems with details of their Mathematica realizations are provided * Comprehensive study of optimal portfolio diversification, including an original theory of optimal portfolio hedging under non-Log-Normal asset price dynamics is presented
The book is designed for the academic community of instructors and students, and most importantly, will meet the everyday trading needs of quantitatively inclined professional and individual investors.
Get Computational Financial Mathematics using MATHEMATICA® by Srdjan Stojanovic at the best price and quality guaranteed only at Werezi Africa's largest book ecommerce store. The book was published by Springer-Verlag New York Inc. and it has 481 pages.
Customers Who Bought This Also Bought

Fooled by Randomness
KSh 2,350.00

Moneyball – The Art of Winning an Unfair Game
KSh 2,500.00
The Intelligent Investor, 3rd Ed.
KSh 5,400.00
World for Sale
KSh 2,150.00
The Intelligent Investor Third Edition
KSh 3,600.00

100 Trillion Dollar Wealth Transfer
KSh 2,350.00
Fooled by Randomness
KSh 3,400.00

Richer, Wiser, Happier
KSh 2,150.00
Same as Ever
KSh 3,050.00
Psychology of Money
KSh 4,500.00
Art of Spending Money
KSh 3,050.00

More Money Than God
KSh 3,050.00
