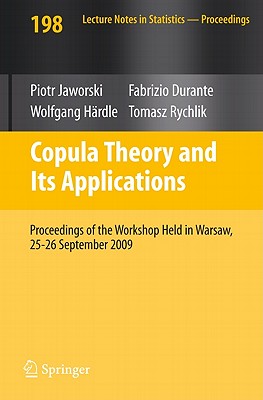
Copula Theory and Its Applications : Proceedings of the Workshop Held in Warsaw, 25-26 September 2009
2010 ed.
Book Details
Format
Paperback / softback
Book Series
Lecture Notes in Statistics
ISBN-10
364212464X
ISBN-13
9783642124648
Edition
2010 ed.
Publisher
Springer-Verlag Berlin and Heidelberg GmbH & Co. KG
Imprint
Springer-Verlag Berlin and Heidelberg GmbH & Co. K
Country of Manufacture
DE
Country of Publication
GB
Publication Date
Jul 24th, 2010
Print length
327 Pages
Weight
538 grams
Dimensions
23.30 x 15.50 x 2.30 cms
KSh 23,400.00
Currently unavailable
0 in stock
Delivery Location
Delivery fee: Select location
Secure
Quality
Fast
Copulas are mathematical objects that fully capture the dependence structure among random variables and hence offer great flexibility in building multivariate stochastic models. This book is divided into two main parts: Part I - "Surveys" contains 11 chapters that provide an up-to-date account of essential aspects of copula models.
Copulas are mathematical objects that fully capture the dependence structure among random variables and hence offer great flexibility in building multivariate stochastic models. Since their introduction in the early 50's, copulas have gained considerable popularity in several fields of applied mathematics, such as finance, insurance and reliability theory. Today, they represent a well-recognized tool for market and credit models, aggregation of risks, portfolio selection, etc. This book is divided into two main parts: Part I - "Surveys" contains 11 chapters that provide an up-to-date account of essential aspects of copula models. Part II - "Contributions" collects the extended versions of 6 talks selected from papers presented at the workshop in Warsaw.
Get Copula Theory and Its Applications by Fabrizio Durante at the best price and quality guaranteed only at Werezi Africa's largest book ecommerce store. The book was published by Springer-Verlag Berlin and Heidelberg GmbH & Co. KG and it has 327 pages.
Customers Who Bought This Also Bought
We Are Not Able to Live in the Sky
KSh 3,400.00
Naked Economics – Undressing the Dismal Science
KSh 2,550.00
Shared Prosperity in a Fractured World
KSh 4,000.00

Principles of Fintech
KSh 8,100.00

The American Meme
KSh 3,950.00

National Accounts Statistics
KSh 16,050.00
Capital Flows and Financial Crises
KSh 20,900.00
Dead Fish Don''t Swim Upstream
KSh 4,150.00
Foreign Direct Investment in the Real and Financial Sector of Industrial Countries
KSh 31,600.00

Program Development, Grantwriting, and Implementation
KSh 15,500.00

From Microfinance to Business Planning: Escaping Poverty Traps
KSh 7,700.00
Essays in Nonlinear Time Series Econometrics
KSh 22,950.00