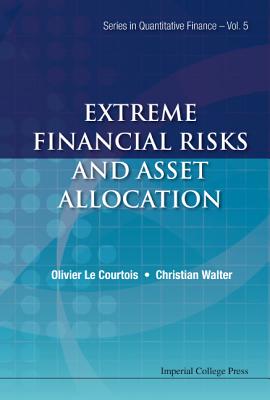
Extreme Financial Risks and Asset Allocation
Book Details
Format
Hardback
Book Series
Series In Quantitative Finance
ISBN-10
1783263083
ISBN-13
9781783263080
Publisher
Imperial College Press
Imprint
Imperial College Press
Country of Manufacture
GB
Country of Publication
GB
Publication Date
Apr 24th, 2014
Print length
372 Pages
Weight
668 grams
Dimensions
15.70 x 23.20 x 2.40 cms
KSh 21,600.00
Currently unavailable
0 in stock
Delivery Location
Delivery fee: Select location
Secure
Quality
Fast
Each financial crisis calls for — by its novelty and the mechanisms it shares with preceding crises — appropriate means to analyze financial risks. In Extreme Financial Risks and Asset Allocation, the authors present in an accessible and timely manner the concepts, methods, and techniques that are essential for an understanding of these risks in an environment where asset prices are subject to sudden, rough, and unpredictable changes. These phenomena, mathematically known as “jumps”, play an important role in practice. Their quantitative treatment is generally tricky and is sparsely tackled in similar books. One of the main appeals of this book lies in its approachable and concise presentation of the ad hoc mathematical tools without sacrificing the necessary rigor and precision.This book contains theories and methods which are usually found in highly technical mathematics books or in scattered, often very recent, research articles. It is a remarkable pedagogical work that makes these difficult results accessible to a large readership. Researchers, Masters and PhD students, and financial engineers alike will find this book highly useful.
Get Extreme Financial Risks and Asset Allocation by Christian Walter, Olivier A Le Courtois at the best price and quality guaranteed only at Werezi Africa's largest book ecommerce store. The book was published by Imperial College Press and it has 372 pages.
Customers Who Bought This Also Bought
We Are Not Able to Live in the Sky
KSh 3,400.00
Naked Economics – Undressing the Dismal Science
KSh 2,550.00
Shared Prosperity in a Fractured World
KSh 4,000.00

Principles of Fintech
KSh 8,100.00

The American Meme
KSh 3,950.00

National Accounts Statistics
KSh 16,050.00
Capital Flows and Financial Crises
KSh 20,900.00
Dead Fish Don''t Swim Upstream
KSh 4,150.00
Foreign Direct Investment in the Real and Financial Sector of Industrial Countries
KSh 31,600.00

Program Development, Grantwriting, and Implementation
KSh 15,500.00

From Microfinance to Business Planning: Escaping Poverty Traps
KSh 7,700.00
Essays in Nonlinear Time Series Econometrics
KSh 22,950.00