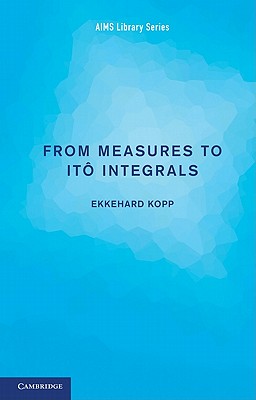
From Measures to Itô Integrals
Book Details
Format
Paperback / softback
Book Series
AIMS Library of Mathematical Sciences
ISBN-10
1107400864
ISBN-13
9781107400863
Publisher
Cambridge University Press
Imprint
Cambridge University Press
Country of Manufacture
US
Country of Publication
GB
Publication Date
Mar 31st, 2011
Print length
128 Pages
Weight
17 grams
Dimensions
21.50 x 13.80 x 0.70 cms
KSh 4,850.00
Currently unavailable
0 in stock
Delivery Location
Delivery fee: Select location
Secure
Quality
Fast
This concise introduction to the background theory of stochastic processes begins with a clear account of measure theory and leads up to the Itô formula and its basic applications in Black–Scholes theory. Ideal for beginning graduate students, this treatment is reasonably rigorous and includes carefully chosen exercises.
From Measures to Itô Integrals gives a clear account of measure theory, leading via L2-theory to Brownian motion, Itô integrals and a brief look at martingale calculus. Modern probability theory and the applications of stochastic processes rely heavily on an understanding of basic measure theory. This text is ideal preparation for graduate-level courses in mathematical finance and perfect for any reader seeking a basic understanding of the mathematics underpinning the various applications of Itô calculus.
Get From Measures to Itô Integrals by Ekkehard Kopp at the best price and quality guaranteed only at Werezi Africa's largest book ecommerce store. The book was published by Cambridge University Press and it has 128 pages.
Customers Who Bought This Also Bought
We Are Not Able to Live in the Sky
KSh 3,400.00
Naked Economics – Undressing the Dismal Science
KSh 2,550.00
Shared Prosperity in a Fractured World
KSh 4,000.00

Principles of Fintech
KSh 8,100.00

The American Meme
KSh 3,950.00

National Accounts Statistics
KSh 16,050.00
Capital Flows and Financial Crises
KSh 20,900.00
Dead Fish Don''t Swim Upstream
KSh 4,150.00
Foreign Direct Investment in the Real and Financial Sector of Industrial Countries
KSh 31,600.00

Program Development, Grantwriting, and Implementation
KSh 15,500.00

From Microfinance to Business Planning: Escaping Poverty Traps
KSh 7,700.00
Essays in Nonlinear Time Series Econometrics
KSh 22,950.00