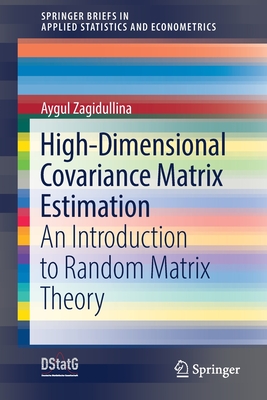
High-Dimensional Covariance Matrix Estimation : An Introduction to Random Matrix Theory
1st ed. 2021
Book Details
Format
Paperback / softback
ISBN-10
3030800644
ISBN-13
9783030800642
Edition
1st ed. 2021
Publisher
Springer Nature Switzerland AG
Imprint
Springer Nature Switzerland AG
Country of Manufacture
GB
Country of Publication
GB
Publication Date
Oct 30th, 2021
Print length
115 Pages
Weight
210 grams
Dimensions
23.30 x 15.50 x 1.00 cms
KSh 10,800.00
Werezi Extended Catalogue
Delivery in 12 days
1 copies in stock
Delivery Location
Delivery fee: Select location
Delivery in 12 days
Secure
Quality
Fast
It draws attention to the deficiencies of standard statistical tools when used in the high-dimensional setting, and introduces the basic concepts and major results related to spectral statistics and random matrix theory under high-dimensional asymptotics in an understandable and reader-friendly way.
This book presents covariance matrix estimation and related aspects of random matrix theory. It focuses on the sample covariance matrix estimator and provides a holistic description of its properties under two asymptotic regimes: the traditional one, and the high-dimensional regime that better fits the big data context. It draws attention to the deficiencies of standard statistical tools when used in the high-dimensional setting, and introduces the basic concepts and major results related to spectral statistics and random matrix theory under high-dimensional asymptotics in an understandable and reader-friendly way. The aim of this book is to inspire applied statisticians, econometricians, and machine learning practitioners who analyze high-dimensional data to apply the recent developments in their work.
Get High-Dimensional Covariance Matrix Estimation by Aygul Zagidullina at the best price and quality guaranteed only at Werezi Africa's largest book ecommerce store. The book was published by Springer Nature Switzerland AG and it has 115 pages.
Customers Who Bought This Also Bought
Lean Analytics – Use Data to Build a Better Startup Faster
KSh 5,750.00
Fooled by Randomness
KSh 3,400.00
Capital and Ideology
KSh 7,450.00
Microeconomics, Global Edition
KSh 15,500.00

The Power of Darkness
KSh 2,000.00

National Accounts Statistics
KSh 16,050.00

Microstructure, Statistical Fluctuations, and Technical Signals in Rational Asset Pricing
KSh 24,650.00
Progress Towards the Sustainable Development Goals in the Arab Region in 2026
KSh 3,700.00
Game Theory
KSh 45,000.00
Essays in Nonlinear Time Series Econometrics
KSh 22,950.00
A Concise Introduction to Econometrics
KSh 18,900.00
A Dynamic Approach to Economic Theory
KSh 33,850.00