
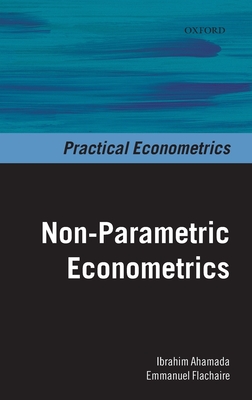
Non-Parametric Econometrics
Book Details
Format
Hardback
Book Series
Practical Econometrics
ISBN-10
0199578001
ISBN-13
9780199578009
Publisher
Oxford University Press
Imprint
Oxford University Press
Country of Manufacture
GB
Country of Publication
GB
Publication Date
Dec 23rd, 2010
Print length
176 Pages
Weight
426 grams
Dimensions
24.10 x 16.30 x 1.60 cms
Product Classification:
EconometricsEconomic statisticsEconomic forecastingApplied mathematics
KSh 18,650.00
Temporarily out of stock, due soon
0 in stock
Delivery Location
Delivery fee: Select location
Secure
Quality
Fast
This volume provides an accessible introduction to nonparametric and semiparametric econometrics for those with a basic understanding of econometrics. This is the second in a series of books designed to provide practitioners, researchers, and students with practical introductions to various topics in econometrics.
This book allows those with a basic knowledge of econometrics to learn the main nonparametric and semiparametric techniques used in econometric modelling, and how to apply them correctly. It looks at kernel density estimation, kernel regression, splines, wavelets, and mixture models, and provides useful empirical examples throughout. Using empirical application, several economic topics are addressed, including income distribution, wage equation, economic convergence, the Phillips curve, interest rate dynamics, returns volatility, and housing prices. A helpful appendix also explains how to implement the methods using R. This useful book will appeal to practitioners and researchers who need an accessible introduction to nonparametric and semiparametric econometrics. The practical approach provides an overview of the main techniques without including too much focus on mathematical formulas. It also serves as an accompanying textbook for a basic course, typically at undergraduate or graduate level.
Get Non-Parametric Econometrics by Emmanuel Flachaire, Ibrahim Ahamada at the best price and quality guaranteed only at Werezi Africa's largest book ecommerce store. The book was published by Oxford University Press and it has 176 pages.
Customers Who Bought This Also Bought
Lean Analytics – Use Data to Build a Better Startup Faster
KSh 5,750.00
Fooled by Randomness
KSh 3,400.00
Capital and Ideology
KSh 7,450.00
Microeconomics, Global Edition
KSh 15,500.00

The Power of Darkness
KSh 2,000.00

National Accounts Statistics
KSh 16,050.00

Microstructure, Statistical Fluctuations, and Technical Signals in Rational Asset Pricing
KSh 24,650.00
Progress Towards the Sustainable Development Goals in the Arab Region in 2026
KSh 3,700.00
Game Theory
KSh 45,000.00
Essays in Nonlinear Time Series Econometrics
KSh 22,950.00
A Concise Introduction to Econometrics
KSh 18,900.00
A Dynamic Approach to Economic Theory
KSh 33,850.00
