
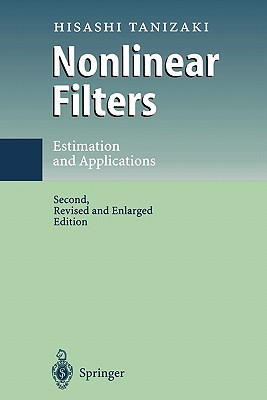
Book Details
Format
Paperback / softback
ISBN-10
364208253X
ISBN-13
9783642082535
Edition
Second Edition 1996
Publisher
Springer-Verlag Berlin and Heidelberg GmbH & Co. KG
Imprint
Springer-Verlag Berlin and Heidelberg GmbH & Co. K
Country of Manufacture
DE
Country of Publication
GB
Publication Date
Dec 1st, 2010
Print length
256 Pages
KSh 16,200.00
Currently unavailable
0 in stock
Delivery Location
Delivery fee: Select location
Secure
Quality
Fast
Nonlinear and nonnormal filters are introduced and developed. Traditional nonlinear filters such as the extended Kalman filter and the Gaussian sum filter give biased filtering estimates, and therefore several nonlinear and nonnormal filters have been derived from the underlying probability density functions.
Nonlinear and nonnormal filters are introduced and developed. Traditional nonlinear filters such as the extended Kalman filter and the Gaussian sum filter give biased filtering estimates, and therefore several nonlinear and nonnormal filters have been derived from the underlying probability density functions. The density-based nonlinear filters introduced in this book utilize numerical integration, Monte-Carlo integration with importance sampling or rejection sampling and the obtained filtering estimates are asymptotically unbiased and efficient. By Monte-Carlo simulation studies, all the nonlinear filters are compared. Finally, as an empirical application, consumption functions based on the rational expectation model are estimated for the nonlinear filters, where US, UK and Japan economies are compared.
Get Nonlinear Filters by Hisashi Tanizaki at the best price and quality guaranteed only at Werezi Africa's largest book ecommerce store. The book was published by Springer-Verlag Berlin and Heidelberg GmbH & Co. KG and it has 256 pages.
Customers Who Bought This Also Bought
Economics Book
KSh 4,250.00
Basic Economics
KSh 6,850.00
The Essential Keynes
KSh 2,350.00
General Theory of Employment, Interest and Money
KSh 1,400.00
The Wealth of Nations – The Economics Classic – A Selected Edition for the Contemporary Reader
KSh 2,350.00
Wealth of Nations
KSh 1,800.00
Equality
KSh 2,150.00
The Wealth of Nations
KSh 2,350.00
What Happened to Liberal Democracy?
KSh 3,050.00

Good Economics for Hard Times
KSh 2,350.00
Naked Economics – Undressing the Dismal Science
KSh 2,550.00
Discrimination and Disparities
KSh 5,400.00

