
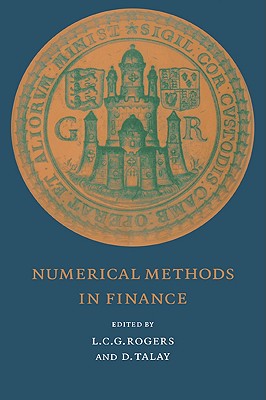
Numerical Methods in Finance
Book Details
Format
Paperback / softback
Book Series
Publications of the Newton Institute
ISBN-10
0521061695
ISBN-13
9780521061698
Publisher
Cambridge University Press
Imprint
Cambridge University Press
Country of Manufacture
GB
Country of Publication
GB
Publication Date
Apr 24th, 2008
Print length
340 Pages
Weight
518 grams
Dimensions
22.90 x 15.30 x 1.90 cms
Product Classification:
FinanceFinance and the finance industryApplied mathematics
KSh 9,900.00
Currently unavailable
0 in stock
Delivery Location
Delivery fee: Select location
Secure
Quality
Fast
Numerical Methods in Finance describes a wide variety of numerical methods used in financial analysis. Articles have been written in a pedagogic style and made reasonably self-contained, covering both mathematical matters and practical issues in numerical problems.
Numerical Methods in Finance has emerged as a discipline at the intersection of probability theory, finance and numerical analysis. This book, based on lectures given at the Newton Institute as part of a broader programme, describes a wide variety of numerical methods used in financial analysis: computation of option prices, especially of American option prices, by finite difference and other methods; numerical solution of portfolio management strategies; statistical procedures; identification of models; Monte Carlo methods; and numerical implications of stochastic volatilities. Articles have been written in a pedagogic style and made reasonably self-contained, covering both mathematical matters and practical issues in numerical problems. Thus the book has something to offer economists, probabilists and applied mathematicians working in finance.
Get Numerical Methods in Finance by Rocquencourt) Talay at the best price and quality guaranteed only at Werezi Africa's largest book ecommerce store. The book was published by Cambridge University Press and it has 340 pages.
Customers Who Bought This Also Bought
We Are Not Able to Live in the Sky
KSh 3,400.00
Naked Economics – Undressing the Dismal Science
KSh 2,550.00
Shared Prosperity in a Fractured World
KSh 4,000.00

Principles of Fintech
KSh 8,100.00

The American Meme
KSh 3,950.00

National Accounts Statistics
KSh 16,050.00
Capital Flows and Financial Crises
KSh 20,900.00
Dead Fish Don''t Swim Upstream
KSh 4,150.00
Foreign Direct Investment in the Real and Financial Sector of Industrial Countries
KSh 31,600.00

Program Development, Grantwriting, and Implementation
KSh 15,500.00

From Microfinance to Business Planning: Escaping Poverty Traps
KSh 7,700.00
Essays in Nonlinear Time Series Econometrics
KSh 22,950.00
