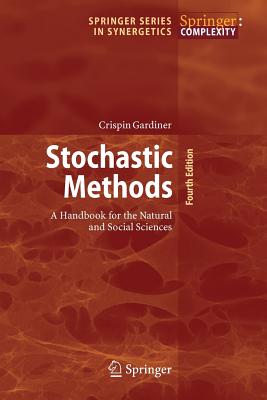
Stochastic Methods : A Handbook for the Natural and Social Sciences
Fourth Edition 2009
Book Details
Format
Paperback / softback
Book Series
Springer Series in Synergetics
ISBN-10
3642089623
ISBN-13
9783642089626
Edition
Fourth Edition 2009
Publisher
Springer-Verlag Berlin and Heidelberg GmbH & Co. KG
Imprint
Springer-Verlag Berlin and Heidelberg GmbH & Co. K
Country of Manufacture
DE
Country of Publication
GB
Publication Date
Oct 19th, 2010
Print length
447 Pages
Weight
674 grams
Dimensions
23.50 x 15.60 x 2.60 cms
Product Classification:
Cybernetics & systems theoryCybernetics and systems theoryEconomic theory & philosophyEconomic theory and philosophyProbability & statisticsProbability and statisticsStochasticsOptical physicsQuantum physics (quantum mechanics & quantum field theory)Quantum physics (quantum mechanics and quantum field theory)Mathematical / Computational / Theoretical physicsMathematical physicsPhysical chemistry
KSh 13,500.00
Temporarily out of stock, due soon
0 in stock
Delivery Location
Delivery fee: Select location
Secure
Quality
Fast
Further, in response to the revolution in financial markets following from the discovery by Fischer Black and Myron Scholes of a reliable option pricing formula, I have written a chapter on the application of stochastic methods to financial markets.
A Historical Introduction.- Probability Concepts.- Markov Processes.- The Ito Calculus and Stochastic Differential Equations.- The Fokker-Planck Equation.- The Fokker-Planck Equation in Several Dimensions.- Small Noise Approximations for Diffusion Processes.- The White Noise Limit.- Beyond the White Noise Limit.- Lévy Processes and Financial Applications.- Master Equations and Jump Processes.- The Poisson Representation.- Spatially Distributed Systems.- Bistability, Metastability, and Escape Problems.- Simulation of Stochastic Differential Equations.
Get Stochastic Methods by Crispin Gardiner at the best price and quality guaranteed only at Werezi Africa's largest book ecommerce store. The book was published by Springer-Verlag Berlin and Heidelberg GmbH & Co. KG and it has 447 pages.
Customers Who Bought This Also Bought
Thinking in Systems
KSh 3,050.00
For Everyone Bible Study Guide: Luke
KSh 1,250.00
The Laws of Thought
KSh 2,000.00
Laws of Thought
KSh 3,050.00
Laws of Thought
KSh 4,500.00
Frankenstein and STEAM – Essays for Charles E. Robinson
KSh 22,300.00

Algorithms in Advanced Artificial Intelligence
KSh 30,950.00

Algorithms in Advanced Artificial Intelligence
KSh 9,350.00
Linear Systems Theory
KSh 37,800.00
Fractals and Chaos
KSh 28,450.00
Theories and Models of Urbanization
KSh 26,800.00
Machine Intelligence and Data Analytics for Sustainable Future Smart Cities
KSh 27,000.00