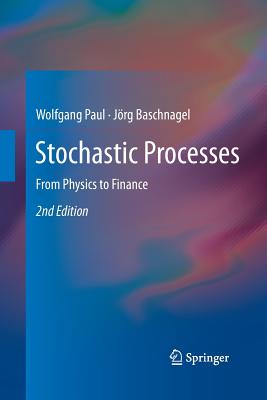
Stochastic Processes : From Physics to Finance
Softcover reprint of the original 2nd ed. 2013
Book Details
Format
Paperback / softback
ISBN-10
3319033786
ISBN-13
9783319033785
Edition
Softcover reprint of the original 2nd ed. 2013
Publisher
Springer International Publishing AG
Imprint
Springer International Publishing AG
Country of Manufacture
GB
Country of Publication
GB
Publication Date
Aug 6th, 2015
Print length
280 Pages
KSh 21,600.00
Currently unavailable
0 in stock
Delivery Location
Delivery fee: Select location
Secure
Quality
Fast
This book introduces the theory of stochastic processes with applications taken from physics and finance. Beyond a presentation of geometric Brownian motion and the Black-Scholes approach to option pricing as well as the econophysics analysis of the stylized facts of financial markets, an introduction to agent based modeling approaches is given.
This book introduces the theory of stochastic processes with applications taken from physics and finance. Fundamental concepts like the random walk or Brownian motion but also Levy-stable distributions are discussed. Applications are selected to show the interdisciplinary character of the concepts and methods. In the second edition of the book a discussion of extreme events ranging from their mathematical definition to their importance for financial crashes was included. The exposition of basic notions of probability theory and the Brownian motion problem as well as the relation between conservative diffusion processes and quantum mechanics is expanded. The second edition also enlarges the treatment of financial markets. Beyond a presentation of geometric Brownian motion and the Black-Scholes approach to option pricing as well as the econophysics analysis of the stylized facts of financial markets, an introduction to agent based modeling approaches is given.
Get Stochastic Processes by Jörg Baschnagel, Wolfgang Paul at the best price and quality guaranteed only at Werezi Africa's largest book ecommerce store. The book was published by Springer International Publishing AG and it has 280 pages.
Customers Who Bought This Also Bought
Thinking in Systems
KSh 3,050.00
For Everyone Bible Study Guide: Luke
KSh 1,250.00
The Laws of Thought
KSh 2,000.00
Laws of Thought
KSh 3,050.00
Laws of Thought
KSh 4,500.00
Frankenstein and STEAM – Essays for Charles E. Robinson
KSh 22,300.00

Algorithms in Advanced Artificial Intelligence
KSh 30,950.00

Algorithms in Advanced Artificial Intelligence
KSh 9,350.00
Linear Systems Theory
KSh 37,800.00
Fractals and Chaos
KSh 28,450.00
Theories and Models of Urbanization
KSh 26,800.00
Machine Intelligence and Data Analytics for Sustainable Future Smart Cities
KSh 27,000.00